Nexo
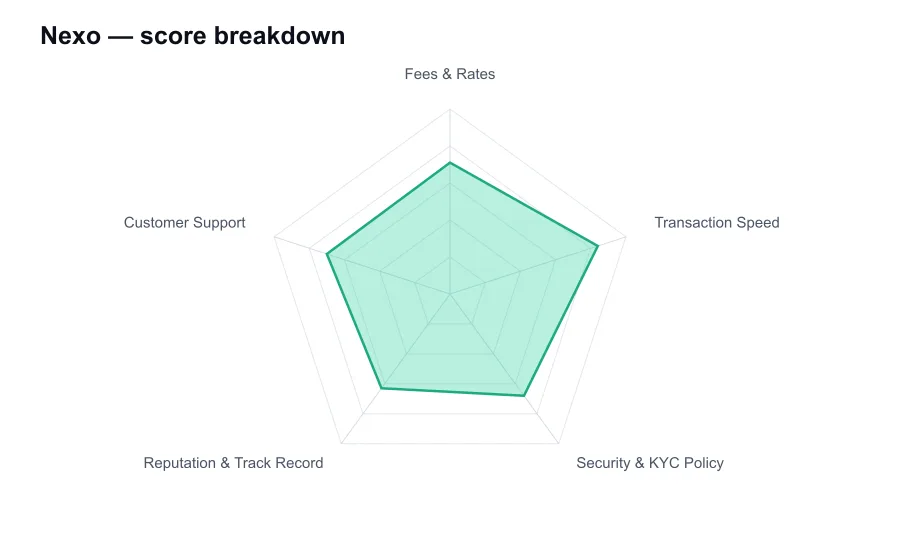
Nexo scores 7.1/10 overall in our independent review, measured against every other provider we've compared, strongest on Transaction Speed (8.4/10) and weakest on Reputation & Track Record (6.3/10).
Score: 7.1 How we score → Status: active (checked 2026-10-13T19:45:08.079Z) Visit official siteEditorial independence: our scores and rankings are produced using the fixed criteria above and are not influenced by advertisers. This is an independent ranking site and is not operated by, or affiliated with, any provider we list.
Affiliate disclosure: some links on this page may earn us a commission at no extra cost to you. This does not affect our rankings.
| Criterion | Score | Note |
|---|---|---|
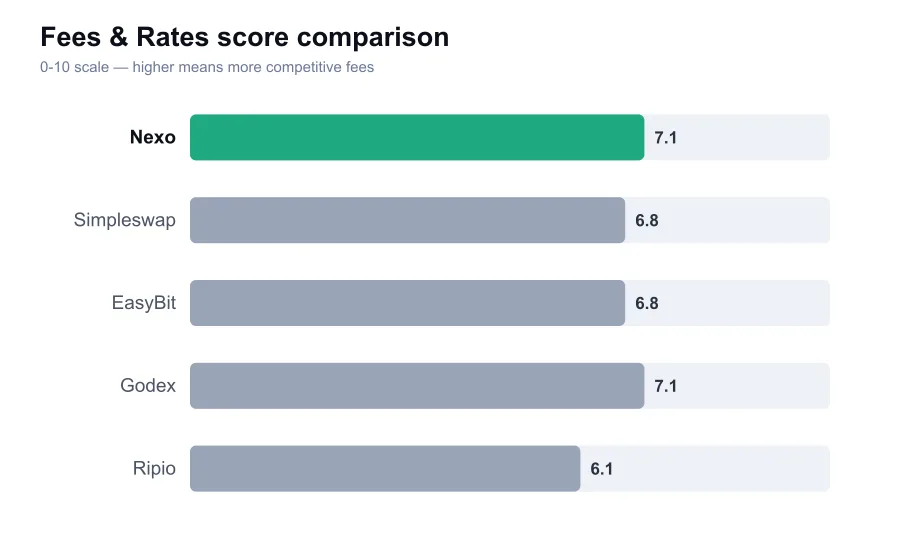
| Fees & Rates | 7.1 | Nexo Pro starts around 0.07% maker and 0.13% taker |
| Transaction Speed | 8.4 | Fast in-app swaps, credit access and internal transfers |
| Security & KYC Policy | 6.8 | Strong account controls, but lending adds counterparty risk |
| Reputation & Track Record | 6.3 | Survived lending-sector failures, with major US settlement |
| Customer Support | 7.0 | Broad help center and app support, complex cases can drag |
| Fact | Value |
|---|---|
| Founded | 2018 |
| Nexo Pro maker fee | From 0.07% |
| Nexo Pro taker fee | From 0.13% |
| US Earn settlement | $45 million in January 2023 |
| Account verification | Required |
| Core products | Lending, swaps, yield and card |
| Pros | Cons |
|---|---|
| Integrated borrowing, swaps, yield and card | — |
| Competitive Nexo Pro spot fees | — |
| Fast internal account movements | — |
| Address whitelisting and two-factor authentication | — |
| Operating since 2018 | — |
What is Nexo?
How Nexo Works
- Create an account and complete verification
- Deposit supported crypto or buy through Nexo
- Choose to hold, swap, use collateral or access eligible yield products
- Monitor loan-to-value ratios if borrowing
- Withdraw assets to an external wallet when needed
KYC
| Requirement | mandatory |
|---|---|
| Notes | Nexo uses identity verification and may request additional documents. Product availability and verification requirements differ by jurisdiction. |
Supported Assets
| Notable Coins | Bitcoin, Ethereum, USDT, USDC, XRP, Solana, Cardano, Polygon, Avalanche, NEXO |
|---|
Availability
| Global? | No |
|---|---|
| Restricted Countries | United States |
| Notes | Services and individual products vary materially by jurisdiction. Nexo phased out its US Earn product. |
How to Use Nexo Safely
- Enable two-factor authentication before depositing
- Whitelist withdrawal addresses where available
- Keep loan-to-value comfortably below the liquidation threshold
- Read the exact yield tier, lock-up and payout conditions
- Do not treat platform yield as a bank savings product
- Test withdrawals with a small amount first
Mobile App
| iOS | Yes |
|---|---|
| Android | Yes |
| Notes | Nexo provides mobile apps for trading, borrowing, account monitoring and card functions. |
Nexo is one of the better-known names in crypto lending, interest products and collateralized borrowing. Its pitch is attractive on paper: deposit digital assets, earn yield, borrow against them rather than selling, swap coins in-app and use a card tied to your holdings. That package has appealed to long-term holders who want their crypto to do more than sit idle. It has also placed Nexo directly in the line of fire from regulators, because yield-bearing crypto accounts are exactly where the industry's most damaging failures have occurred.
The company was founded in 2018 and grew rapidly during the lending boom. Unlike a normal spot exchange, Nexo is built around custody and credit. Customers hand assets to the company, which then uses a risk-management and lending model to provide credit products and rewards. That distinction is essential. A Nexo balance is a claim on Nexo, not coins under your own direct control. The convenience is real, but so is the counterparty exposure.
The app is polished and generally easier to use than a traditional exchange. Users can buy or swap supported assets, transfer collateral into credit lines, earn interest on eligible balances and spend through the Nexo Card. There is also Nexo Pro, a separate trading platform offering order-book trading with maker and taker pricing. The result is a broad product range that can feel unusually complete for one account, especially to someone who dislikes moving funds between an exchange, a wallet and a lender.
Fees need to be separated by product because the headline can mislead. Nexo's retail exchange function does not present itself like a simple flat-fee order book, and the effective cost can include spread. That may be acceptable for a quick rebalance, but users should not assume a supposedly free swap is cheaper than trading on Kraken Pro or Coinbase Advanced. Nexo Pro has publicly listed lower spot trading tiers, including maker fees around 0.07 percent and taker fees around 0.13 percent at the entry level, which is much more competitive.
Borrowing is where many customers make expensive mistakes. Nexo advertises loan rates that depend on loan-to-value ratio, loyalty tier and the assets pledged. The lowest advertised rate is not what every customer receives, and a borrower who pushes loan-to-value too hard can face collateral repayments or liquidation pressure during a sharp sell-off. A loan against Bitcoin can look clever in a rising market. In a 30 percent drawdown, the mechanics become painfully real.
Nexo's yield rates also require careful reading. Returns can vary by asset, lock-up choice, loyalty tier and whether the customer elects to receive rewards in NEXO tokens. A rate shown as high as a headline figure may involve a fixed term or token-based bonus. That does not make the product deceptive, but it does mean a user should read the exact tier and payout currency before depositing. Stablecoin yields deserve particularly close scrutiny because the return comes with issuer and platform risk, not just Nexo risk.
Speed is usually a strength inside Nexo. Transfers between product sections, swaps and credit-line access are designed to be near immediate once funds are credited. Crypto deposits and withdrawals still rely on confirmations, compliance screening and network conditions. Nexo has historically promoted a number of free crypto withdrawals according to loyalty level, though limits and supported networks can change. Users should always check whether an asset is being sent on the correct network, because a cheap network choice can become an expensive recovery request if the destination does not support it.
The security package is serious enough to be better than the average small exchange. Nexo offers two-factor authentication, address whitelisting and withdrawal confirmation controls. It has also publicized custody arrangements and insurance coverage through third-party custodians. Those measures reduce operational risk, but they should not be confused with deposit insurance or a guarantee of repayment if Nexo itself failed. The collapse of Celsius and BlockFi showed why that distinction matters more than marketing language about secure storage.
KYC is mandatory for meaningful use of Nexo. The company has multiple verification levels and can ask for further information under anti-money-laundering procedures. That is no surprise given that it offers lending, cards and fiat-linked services. It does mean that people seeking anonymous borrowing or frictionless access will be disappointed. Nexo can also restrict products by jurisdiction, and the availability of Earn, borrowing and the card is not uniform around the world.
Its regulatory history is mixed. In January 2023, Nexo agreed to pay $45 million to settle US Securities and Exchange Commission and state allegations tied to its Earn Interest Product, without admitting or denying the allegations. Nexo had already announced it would phase out its US Earn product. That settlement is not a minor footnote. It demonstrated that a lending company can be operationally sophisticated and still run into a fundamental conflict with regulators over how its yield products are offered.
The company also faced public scrutiny after Bulgarian authorities searched offices in early 2023 as part of an investigation. Bulgarian prosecutors later closed the case, saying they found no evidence supporting the alleged criminal conduct. Nexo supporters understandably point to that outcome. Critics are also justified in remembering how much uncertainty the event created. The important lesson is that crypto lenders carry legal and operational risks that are harder to evaluate than those of a simple spot-only exchange.
Nexo's reputation is stronger than many lending platforms because it has continued operating through a brutal period for the sector, including the failures of Celsius, BlockFi, Voyager and FTX. It has made efforts to publish real-time reserve information and communicate its risk model. Still, proof-of-reserves style reporting is not the same as a full independent financial audit of every liability, loan and contingent risk. Customers should view it as useful evidence, not final proof that a lender is immune to stress.
Support is generally accessible through app and web channels, and Nexo has a large self-help knowledge base. Routine matters tend to be manageable. The harder cases involve compliance holds, card disputes, loan liquidations and unsupported transfers, where support quality is judged by actual resolution rather than quick first replies. A user borrowing against volatile collateral should not depend on support rescuing a position after a margin threshold has already been crossed.
Nexo is compelling for experienced holders who understand collateral ratios, accept custodial risk and want borrowing or yield in one interface. It is not a savings account and should never be treated like one. The platform's pricing and product design are better than much of the crypto lending field, but its regulatory history and inherent counterparty risk keep it well below the safety profile of self-custody. Use it selectively, avoid stretching leverage and do not park money there that you cannot afford to have temporarily inaccessible.
What were the Nexo US regulatory settlements?
In January 2023, Nexo agreed to pay $45 million to settle SEC and state allegations relating to its Earn Interest Product, without admitting or denying the allegations.
Are Nexo Pro trading fees competitive?
Nexo Pro has listed entry-level spot fees around 0.07 percent maker and 0.13 percent taker. Retail in-app swaps can have a separate spread.
Does Nexo require KYC?
Yes. Nexo requires identity verification for meaningful account use and can request more documents under anti-money-laundering procedures.
Can a Nexo loan be liquidated?
Yes. If collateral value falls and your loan-to-value ratio crosses Nexo's thresholds, repayment or collateral management may be required. Borrowers should leave a large safety buffer.
Is Nexo Earn available everywhere?
No. Earn and other Nexo products vary by jurisdiction. Nexo phased out its US Earn product before the January 2023 settlement.
Did the Bulgarian investigation against Nexo lead to charges?
Bulgarian prosecutors closed the investigation in 2024, stating that they found no evidence supporting the alleged criminal conduct. The episode still created reputational uncertainty.
Are Nexo balances protected like bank deposits?
No. Assets held with Nexo involve platform and counterparty risk. Custody arrangements and security controls do not turn a crypto balance into an insured bank deposit.
Editorial independence: our scores and rankings are produced using the fixed criteria above and are not influenced by advertisers. This is an independent ranking site and is not operated by, or affiliated with, any provider we list.
Affiliate disclosure: some links on this page may earn us a commission at no extra cost to you. This does not affect our rankings.